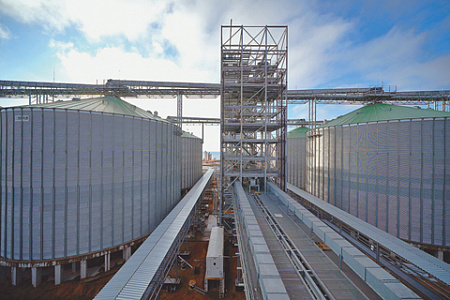
Both Russian and international analysts downgraded their forecasts for Russian grain exports on Monday, citing continued disruption to shipments through Black Sea ports, the main outlet for agricultural exports. Meanwhile, experts raised their estimates for grain carryover stocks. The more grain Russia fails to sell abroad, the greater the downward pressure on domestic purchase prices, they warn. This, in turn, is forcing farmers to cut spending on the next harvest.
For now, Russia is buying more food than it sells. Over the first eight months of this year, exports of food products and agricultural raw materials, excluding textiles, rose 20% YoY totalling USD 28.6 bln. Imports of food and agricultural products rose 4.8% over the same period to USD 29.1 bln, the Federal Customs Service said on Monday
Russia has therefore once again become a net food importer, as it was last year. In 2025, agricultural exports shrank by 4% to USD 40.9 bln, while imports rose by 15% to USD 43.4 bln.
Grain is the mainstay of Russia’s agricultural exports. Last year, it accounted for 27% of all food exports by value. However, its share is declining as overall shipments fall, down from 37% of total agricultural exports in 2024.
On Monday, the US Department of Agriculture cut its forecast for Russian wheat exports in the 2026/27 marketing year by 3 mln tonnes to 40 mln tonnes. A month earlier, it had also lowered the forecast by 3 mln tonnes, from 46 mln.
The forecast for Russia’s wheat carryover stocks at the end of the season, on June 30, 2027, was also raised to 19,030 mln tonnes from 16,090 mln tonnes a month earlier. The estimate for this season’s wheat harvest was left unchanged at 88 mln tonnes.
Notably, the US Department of Agriculture does not include data from Crimea or the territories Russia claims as its own in its estimates for the country
The Institute for Agricultural Market Studies (IKAR) also downgraded its forecast for Russian wheat exports on Monday, to 42 mln tonnes from 43.5 mln previously. The institute estimates the wheat harvest at 88 mln tonnes.
‘We are cutting our estimate for the overall grain harvest from 138 to 137 mln tonnes and export potential from 55 to 52.8 mln tonnes,’ IKAR CEO Dmitri Rylko told Interfax. Under a stress scenario, however, actual grain exports could be much lower, at around 35 mln tonnes, he added. Rylko previously said Russia could fail to export 14–15 mln tonnes of wheat in the 2026/27 marketing year because of logistics constraints in the Azov-Black Sea basin (see Nezavisimaya Gazeta dated October 1, 2026)
By comparison, Russia exported 61 mln tonnes of grain in the 2025/26 marketing year, of which 47 mln tonnes was wheat.
Russian grain shipments have been declining since the start of the new marketing year. Dmitri Rylko previously said wheat exports exceeded 2.4 mln tonnes in September. In total, between June and September they amounted to 6.4 mln tonnes.
According to the Rusagrotrans analytical centre, Russia exported almost 2.7 mln tonnes of wheat in September, compared with 4.9 mln tonnes in the same month last year. The centre estimates possible Russian wheat exports at 6.6 mln tonnes between July and September
August shipments were also sharply lower. The Russian Grain Union (RGU) put wheat exports at 1.3 mln tonnes, down 3.8 times YoY and the lowest since 2017.
The main driver for the decline in exports is the suspension of Azov-Black Sea ports and disruptions to established grain export routes.
Amid logistics constraints in the Azov-Black Sea basin, exporters are trying to redirect shipments. According to Rusagrotrans estimates, around 80% of shipments in September were routed through Baltic Sea ports or towards Central Asian markets
Rylko said more than 1 mln tonnes of wheat were transported by rail in September, while Baltic ports handled more than 1 mln tonnes, a record for wheat shipments through the region. By comparison, just 0.18 mln tonnes of grain were exported through the port of Novorossiysk in September, down from almost 2.4 mln tonnes a year earlier
The Russian Union of Grain Exporters (UGE) estimates the country’s export potential at more than 60 mln tonnes in the 2026/27 marketing year, but logistics constraints are eroding the competitiveness of Russian shipments
Exporters are exploring options to route shipments through Chinese ports and expand transshipment capacity in the Russian Far East. Chinese ports could serve as transit hubs for shipments to various markets, Kseniya Bolomatova, executive director of UGE, has suggested.
Baltic ports can serve Russia’s traditional grain export markets, including the Middle East, Turkey, North Africa and parts of Asia. However, shipping grain to Southeast Asian markets, particularly Indonesia, is more difficult and costly, making Russian grain less competitive, Bolomatova said.
She added that terminal infrastructure in the Russian Far East needed expanding. ‘There are more than 10 terminals there with experience in grain transshipment. We have now brought additional terminals online, and established operators are actively expanding infrastructure and storage capacity,’ she said.
‘The port of Slavyanka, for example, is commissioning a deep-water berth. We expect it to handle up to 200,000 tonnes a month. This would allow us to supply Indonesia and Bangladesh and, in effect, reach not only our largest importers but all our main buyers across more than 100 countries.’
The UGE believes other exporters would be unable to fully offset any shortfall in Russian grain shipments. ‘Other exporters do have some spare capacity, but it is very limited. This would have serious consequences for the global market. Some buyers will inevitably receive less grain than they had expected. What they do receive will also be more expensive. We are already seeing prices jump by 30%,’ Bolomatova warned.
With the Russia-Ukraine conflict ongoing, Russian grain exports via traditional routes remain severely constrained, said Alexander Potavin, an analyst at Finam.
‘The main grain export route previously ran through Russia’s southern ports on the Sea of Azov and the Black Sea. That route has now been disrupted. Alternatives exist, but they are longer, more expensive and are not yet capable of handling the same volumes. ‘Agricultural products can be shipped through Baltic ports, including Ust-Luga. This route works for deliveries to Turkey, North Africa and the Middle East, but grain from southern Russia has to travel much farther, pushing up costs. Routes through the Russian Far East are more convenient for Asian buyers, but additional rail and port capacity is needed. As a result, disruption to shipments through Azov-Black Sea ports and the risks of transporting grain across the Black Sea are making it more difficult to sell this year’s harvest abroad,’ he said.
The more grain is left unsold going into the next season, the greater the downward pressure on domestic purchase prices.
‘Farmers also have to pay for storage, wait longer for revenue and have less money available to service loans and finance the next planting season. By the end of the year, at least 20–35 mln tonnes of grain are likely to remain unsold, piling up and rotting in overloaded grain elevators while farmers face additional costs,’ Potavin said ‘High stocks are weighing on domestic prices, pushing them below production costs. This reduces incentive to spend on the next harvest, from cutting planted areas to applying less fertiliser,’ added Denis Ternovsky, an expert at the Gaidar Institute for Economic Policy.
Potavin cited a survey of 1,000 farms showing that 26% of agricultural producers have abandoned winter wheat sowing entirely this year, while 32% plan to reduce the area planted, and only 29% intend to maintain planting at previous levels.
Rising grain carryover stocks pose a risk if storage capacity proves insufficient, said Anastasiya Prikladova, associate professor at Plekhanov Russian University of Economics. She believes that the forecast of 19 mln tonnes of wheat exceeds the 15–17 Plekhanov Russian University of Economics tonnes recorded in recent years. This places additional strain on the sector.